A $100,000 salary sounds like plenty until life starts giving it jobs. Rent or a mortgage, children, insurance, and savings goals all find places for that money to go.
Neither figure shows how comfortably someone lives. For that, start with the bills that return every month.
First, define who earns the $100,000
Payroll work taught me that matching salaries don’t guarantee matching deposits.
Before calculating anything, we need to know whose paycheck we’re discussing.
Our example uses these assumptions:
- One employee earns $100,000 in regular W-2 wages throughout 2026.
- The worker files as single, is under 65, and has no dependents.
- They claim the standard deduction, with no additional income, deductions, or tax credits.
- They live and work somewhere with no state or local income tax.
That last assumption is important. If you owe state or local income tax, your result will be lower, all else equal.
We’re calculating annual tax estimates and dividing by twelve. Actual deposits depend on payroll timing and withholding settings.
A married couple, a parent claiming eligible credits, or someone paying for family health coverage needs a separate calculation.
Federal taxes bring the monthly figure below $6,600
The 2026 IRS tax adjustments set the single standard deduction at $16,100, up from $15,750 in 2025. Before retirement contributions, that leaves $83,900 of taxable income.
Using the bracket rates, federal income tax is $1,240 on the first $12,400, $4,560 on the next $38,000, and $7,370 on the remaining $33,500.
| Annual calculation | Amount |
|---|---|
| Gross wages | $100,000 |
| Estimated federal income tax | −$13,170 |
| Employee Social Security tax | −$6,200 |
| Employee Medicare tax | −$1,450 |
| Remaining before benefits and savings | $79,180 |
That leaves $6,598.33 monthly on average. The worker reaches the 22% income-tax bracket, but doesn’t pay 22% on every dollar earned.
Retirement savings change the deposit again
Now we’d add the choices hiding behind the salary figure. Suppose this worker contributes 6%, or $6,000 annually, to a traditional 401(k).
Under the IRS rules for traditional 401(k) contributions, that reduces current federal taxable income, but not Social Security or Medicare wages. Estimated federal income tax falls to $11,850.
After the contribution and federal taxes, the worker has $74,500 annually, or $6,208.33 monthly. Putting $500 a month into retirement has reduced available cash by $390 because of the current income-tax saving.
Money going into a retirement account is still savings. It shouldn’t be counted as money lost to taxes.
We’ve assumed no other pretax deductions. Below, health insurance costs $200 monthly from after-tax money. An employer’s pretax health plan would change the calculation. Check your pay stub before subtracting insurance again.
Here’s where the remaining money could go
Groceries need a line in the budget, and so do the less interesting purchases, including detergent, prescriptions, and replacement tires.
For our single renter, here is an illustrative monthly budget using $6,208.33 after taxes and retirement contributions. The figures are chosen examples, not national averages, and include applicable purchase taxes.
| Monthly expense | Amount |
|---|---|
| Rent and renters insurance | $1,800 |
| Utilities, phone, and internet | $300 |
| Groceries | $450 |
| Car payment, fuel, and auto insurance | $650 |
| Health premium and other medical expenses | $325 |
| Other debt payments | $250 |
| Household supplies, clothing, and personal care | $225 |
| Total expenses | $4,000 |
Retirement savings are already funded above. Childcare, dependents, and major medical bills aren’t included.
A different rent changes the calculation
In that example, $100,000 provides room to save. We wouldn’t describe every six-figure earner as barely getting by.
But raise the housing line from $1,800 to $3,000, leaving everything else unchanged, and the remaining money after the same reserves and recreation allowance falls from $1,508.33 to $308.33.
“The chart below shows what remains for other goals at each housing cost, with the same salary and all other expenses unchanged.”
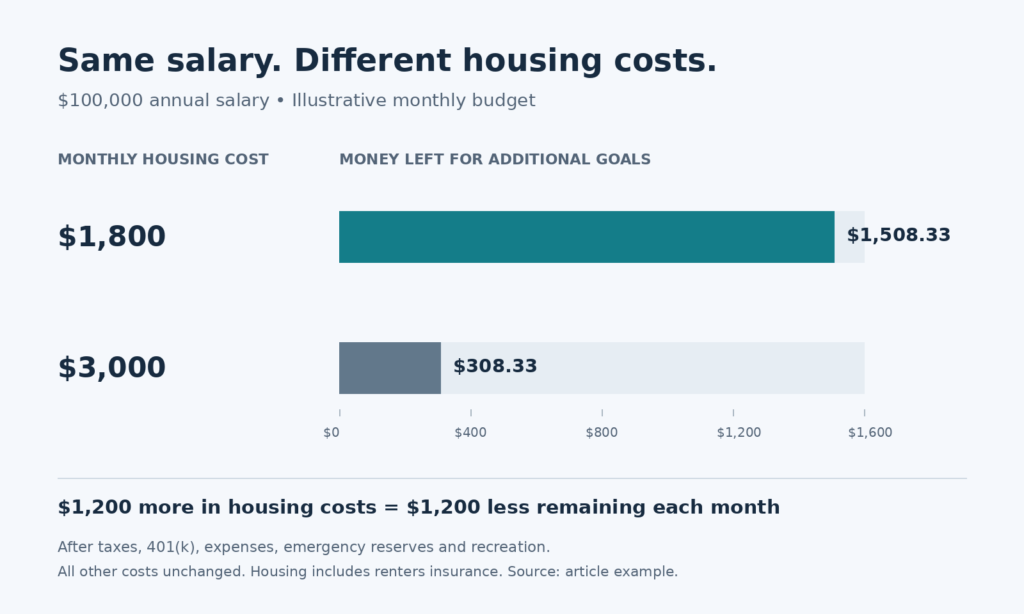
A $900 car repair would consume nearly three months of that remaining margin.
A family cannot simply reuse a single-renter budget. Family insurance, childcare, and food costs need their own entries, alongside the actual tax treatment of the household.
Before accepting a job or signing a lease, compare the expected deposit with housing, commuting, and benefit costs. A higher salary can still leave less room if the expenses attached to it rise faster.
Frequently asked questions
Build the budget from the paycheck upward
We’d start with a recent pay stub, the lease or mortgage statement, and the last three months of spending.
If the mortgage will outlast your working years, check how retirement with a mortgage would change that same budget when wages stop.
Write down what reaches the bank, then mark the insurance and retirement contributions already deducted so they don’t appear twice.
Next, add the bills that arrive annually and divide them by twelve.
In the example above, the difference between $1,508.33 and $308.33 left each month came entirely from housing.
Before committing to a bigger payment, put it into your own spreadsheet and see what remains for the next car repair. The salary alone won’t answer that question.