For a growing share of older homeowners, that includes a mortgage.
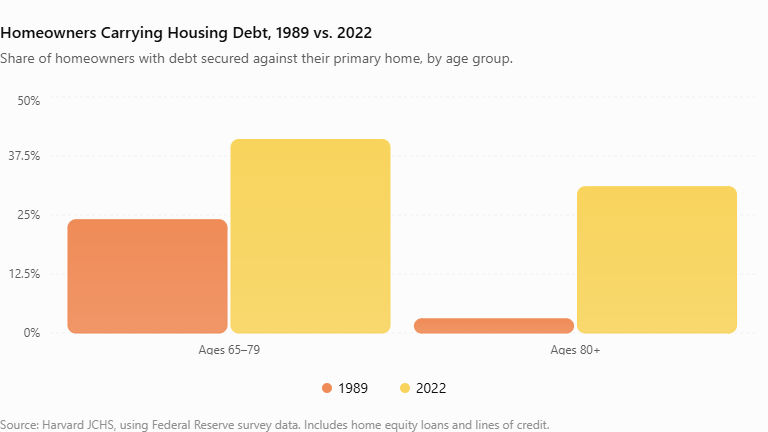
Harvard research found that 41% of homeowners ages 65–79 carried housing debt in 2022, compared with 24% in 1989. Those are retirement-age households, not necessarily retired people. But the question they raise is personal: how comfortably can you keep the house when your paycheck stops?
The mortgage numbers need their dates attached
A number is only useful once you know what it actually represents. The Housing America’s Older Adults 2023 report from the Harvard Joint Center for Housing Studies compares mortgage borrowing in 1989 and 2022, using Federal Reserve survey data.
- Among homeowners ages 65–79, the share carrying mortgages rose from 24% to 41%.
- Among homeowners ages 80 and older, it rose from 3% to 31%.
- The measure includes home equity loans and lines of credit secured against the primary home.
We’re discussing the findings in 2026, but they aren’t a new count of people retiring this year. The Federal Reserve’s published survey results still list 2022 as the latest available dataset.
The increase describes a long-term shift among older homeowners. It doesn’t tell us that every borrower is struggling or that renters are included in those percentages.
A mortgage can outlast the working years
Housing decisions rarely happen in isolation. They have to fit the life around them, including schools, work, and the space a family needs at the time.
Consider someone who takes a 30-year mortgage at 45. Without early repayment, the scheduled finish line is 75. Nothing has to go wrong for that loan to overlap retirement.
Refinancing can also move the payoff date. Replacing a loan with 18 years remaining with a new 30-year loan adds 12 years to the schedule, assuming regular payments.
A smaller monthly payment can come from spreading repayment over more years. It doesn’t necessarily mean the borrowing costs less overall.
The CFPB’s explanation of refinancing costs and loan terms makes that distinction. I’d check the final payment date alongside the monthly amount.
Income changes deserve the same attention as mortgage terms. For example, accepting a pay cut for a four-day workweek could affect how comfortably a household manages its mortgage payments and retirement savings.
What one payment does to a retirement budget
Monthly numbers are more revealing than a mortgage balance. Here is an illustrative budget for a retired couple. It does not describe a real household or the median U.S. household.
Assume $4,500 monthly income after taxes and deductions, with healthcare below excluding premiums already deducted.
| Monthly expense | Amount |
|---|---|
| Mortgage principal and interest | $1,200 |
| Property taxes and homeowners insurance | $450 |
| Utilities, phones, and internet | $350 |
| Food and household supplies | $650 |
| Transportation | $450 |
| Additional healthcare costs | $400 |
| Repairs and irregular expenses reserve | $400 |
| Total allocated | $3,900 |
| Remaining | $600 |
For retirees depending mainly on Social Security, the margin can be even smaller. Our breakdown of living on $2,000 a month in America shows how Medicare, rent, and groceries can consume most of a monthly benefit.
That leaves $600 for recreation, gifts, and anything omitted. A hypothetical $300 increase in recurring costs cuts the margin in half. If investments fund part of the income, a market decline can make withdrawals harder to sustain.
Food spending deserves a closer look when the monthly margin is narrow. A structured list, such as the 5-4-3-2-1 grocery shopping method, may help reduce unnecessary purchases, although it does not cover every household essential or guarantee a lower bill.
Paying off the mortgage would release $1,200 monthly. Taxes, insurance, upkeep, and utilities would remain. A house never entirely stops sending bills.
A mortgage is not the only expense that can follow parents into retirement. Financial support for adult children who have already moved out can also reduce the money available for savings, housing costs, and unexpected bills.
Paying off the loan can leave another problem
Before clearing a mortgage, it helps to look at both sides of the balance sheet. A low fixed rate and an affordable payment may justify keeping cash available. Higher interest costs or a strained budget may strengthen the case for repayment. Expected investment returns are not guaranteed.
Emptying savings to eliminate the payment can leave a homeowner needing to borrow again after a major repair. Taking money from a traditional IRA can also create taxable retirement withdrawals.
Before a large payoff, compare interest saved, taxes triggered, and cash remaining. For a substantial withdrawal, consider having a qualified tax professional check the calculation.
Compare the full cost of each option
Someone might enjoy attempting minor home repairs, but enthusiasm doesn’t replace a roof. A retirement housing plan needs room for expenses that arrive irregularly and refuse to stay small.
We’d compare three routes with actual figures:
- Keep the mortgage and check that expected retirement income covers the payment, other essentials, and a repair reserve.
- Make extra principal payments while preserving emergency savings. Ask the servicer how to direct the money correctly.
- Downsize after subtracting selling expenses, moving costs, and the cost of the replacement home. Smaller doesn’t automatically mean cheaper.
Moving to a less expensive city can also change a household’s long-term housing costs.
The Tulsa Remote relocation program offers an example of how lower living expenses can influence relocation decisions, although its $10,000 incentive is intended for eligible employed remote workers, not retirees.
Refinancing deserves a separate calculation using the offered rate, fees, and payoff date. It won’t automatically improve an existing low-rate loan.
Relocating to a lower-cost state is another option worth evaluating. Our ranking of the best states for retirement on $3,000 a month compares housing, taxes, and healthcare costs across ten states to show where a fixed retirement income may stretch further.
If payments are already becoming difficult, contact the servicer and a HUD-approved housing counselor early. A loan modification may be available, but eligibility and terms vary.
Frequently asked questions
Put the payoff date beside the retirement date
Next step would be a small addition to the household spreadsheet: the expected retirement date beside the scheduled mortgage payoff date. Then replace wages with expected retirement income and keep the housing expenses visible.
We’d run the budget again with higher insurance costs, a major repair, and reduced household income. If the numbers only work when every month behaves itself, the plan needs adjusting.
Before sending extra money to the lender, write down the payment it will eventually remove and the accessible savings it will leave behind. Both figures belong in the conversation.
- Review the timeline: Match your expected retirement date directly against the scheduled mortgage payoff date to avoid surprises.
- Test the budget: Run the numbers with higher insurance, major repairs, and reduced income to ensure it can survive a bad month.
- Calculate the trade-off: Weigh the payment removed against the emergency cash left behind before sending extra money to the lender.