For a plumber or an electrician, a reliable vehicle is part of the job. The loan payment sits on the books every month, next to fuel and insurance, and it raises a question that comes up again and again.
How much does the payment leave for everything else?
New data from Edmunds puts a national number on that question. In the third quarter of 2026, the average new car payment reached a record $787 a month.
Measured against the typical American household income, before a single tax comes out, that payment takes almost 11 cents of every dollar. After taxes, the share grows.
Where the $787 Figure Comes From
The figure covers new vehicles bought with a loan from July through September 2026.
Edmunds released its report on October 1, and Auto Remarketing listed six new records in the Edmunds third-quarter data. A year earlier, the average payment was $756.
- The average amount financed rose to $44,664.
- About 21.2% of financed new purchases carried a payment of $1,000 or more.
- Loans of 84 months or longer made up 25.5% of financed purchases.
- Buyers will pay an average of $9,938 in interest over the life of the loan.
- The average interest rate held at 7.0%.
An average can hide a lot. Buyers with large payments pull the figure up, and buyers who paid cash do not appear in it at all, since the report counts only financed purchases.
How Much of a Median Income $787 Takes
The Census Bureau reported in September that median household income reached $87,460 in 2025, the highest on record.
Many car buyers rely on one paycheck, so we also checked individual pay.
Bureau of Labor Statistics figures for the second quarter of 2026 put median weekly earnings for full-time wage and salary workers at $1,258.
| Income measure | Gross monthly income | Share taken by $787 | Share taken by $1,000 |
|---|---|---|---|
| Median household ($87,460 a year) | $7,288 | 10.8% | 13.7% |
| Median full-time worker ($1,258 a week) | $5,451 | 14.4% | 18.3% |
Both rows use gross income, meaning pay before taxes. The right row depends on how many paychecks cover the car.
Either way, housing takes the first slice, and the car payment competes for what remains.
Take-Home Pay Makes the Share Bigger
Payroll work taught me that nobody pays a car loan with gross income. The payment comes out of whatever lands in the bank account.
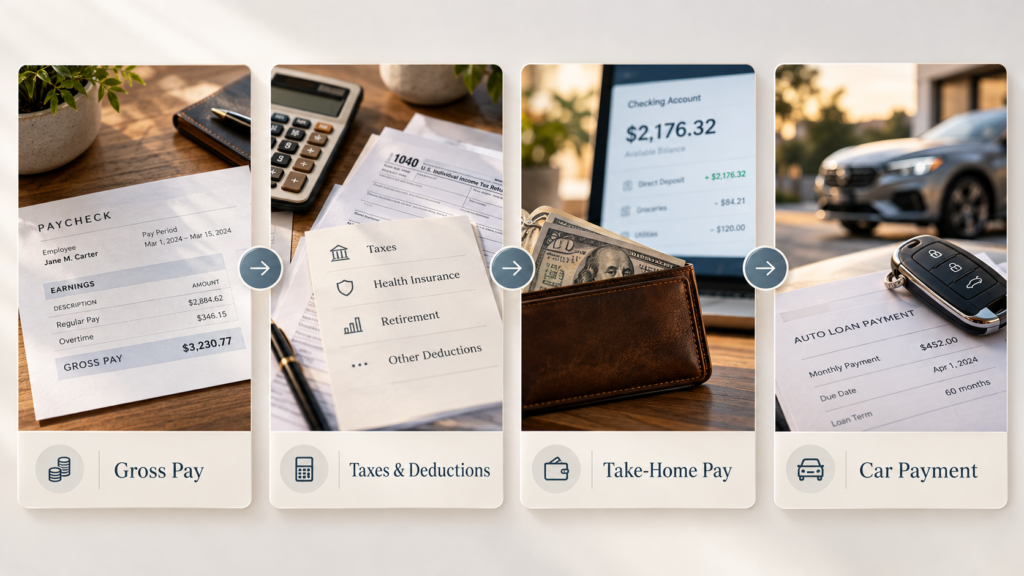
Gross pay is income before any deductions. Net pay, often called take-home pay, is what remains after income taxes, Social Security and Medicare, and deductions such as health insurance premiums or retirement contributions.
We built a hypothetical household, a married couple filing jointly with no children and $87,460 in combined wages.
Using the 2026 standard deduction and tax brackets from the IRS, federal income tax comes to about $6,135, and Social Security and Medicare take about $6,691.
That leaves roughly $6,220 a month after federal taxes. The $787 payment takes 12.7% of it, before state income tax, health premiums, or retirement savings come out.
The Payment Is Only Part of What a Car Costs
A loan payment covers the car. Gas, insurance, and tires are separate.
In September, AAA estimated that owning and operating a new vehicle costs $12,863 a year, or about $1,072 a month, based on 75,000 miles over five years.
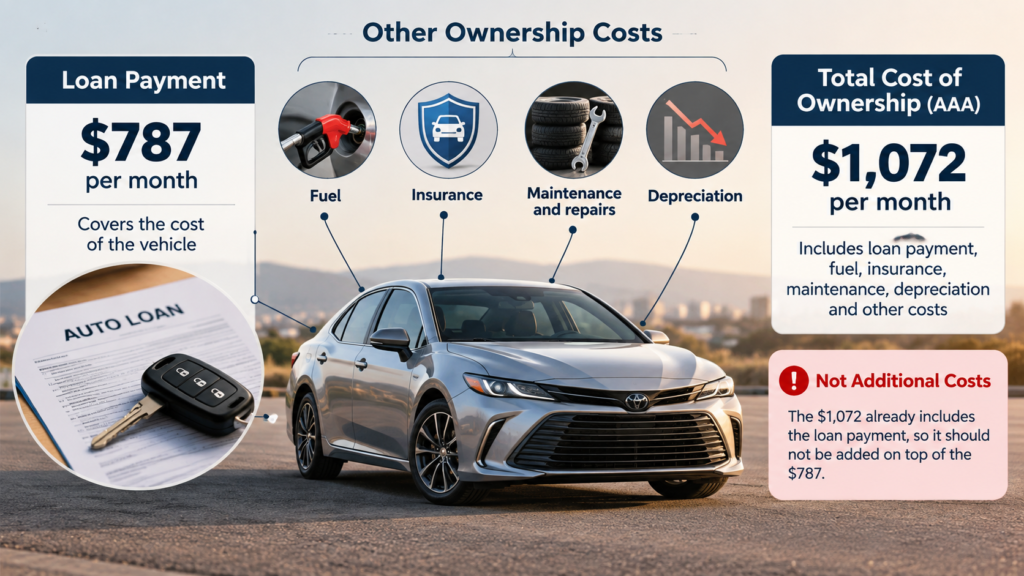
Adding that figure on top of the $787 would double count. AAA includes depreciation, the value a car loses over time, and finance charges, so part of the loan payment already sits inside its total.
One car repair can rearrange a month of family spending, and the payment is the predictable part.
Look at this curiosity. AAA changed its method for 2026 and added electric and hybrid models to its standard comparisons.
The 2026 estimate should not be compared directly with the 2025 figure of $11,577, so the gap is not a true one-year increase.
Longer Loans Lower the Payment and Raise the Interest
Payments would be higher still if buyers were not stretching their loans.
A quarter of financed new purchases now run 84 months or more, which means seven years of payments.
To show the trade, we ran the average amount financed, $44,664, at the average 7.0% rate across four loan lengths.
| Loan length | Monthly payment | Total interest |
|---|---|---|
| 48 months | $1,070 | $6,674 |
| 60 months | $884 | $8,400 |
| 72 months | $761 | $10,162 |
| 84 months | $674 | $11,960 |
Moving from five years to seven saves about $210 a month and adds about $3,560 in interest.
Those are my calculations, not Edmunds figures. Real loans vary with credit scores, down payments, and dealer incentives.
A seven-year loan also gives the balance more time to sit above what the car is worth, which leads to the next problem.
Trade-Ins That Still Owe Money Raise the Stakes
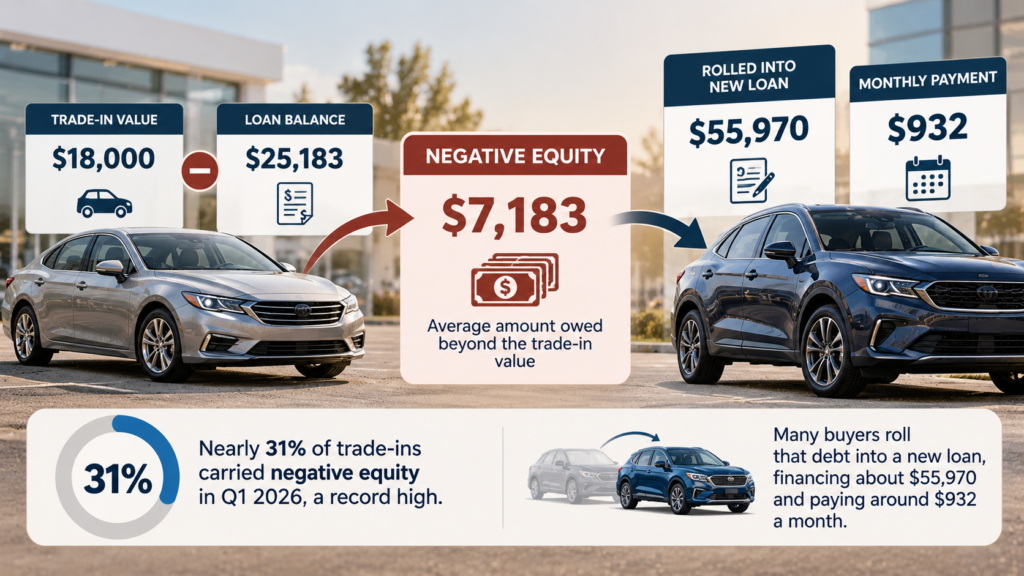
A car can lose value faster than its loan balance shrinks, leaving the owner owing more than the car is worth.
Lenders call that negative equity, and Edmunds figures for the first quarter of 2026, reported by Yahoo Finance, show how common it has become.
- Nearly 31% of trade-ins carried negative equity, a first-quarter record.
- The average amount owed beyond the trade-in value was $7,183.
- Buyers who rolled that debt into a new loan financed about $55,970 and paid around $932 a month.
In bookkeeping for tradespeople, we watched for that math whenever a work truck was traded early.
Any leftover balance moves into the next loan, so the owner keeps paying for a truck that is no longer in the driveway.
The Car Loan Interest Deduction Helps Only Some Buyers
A federal tax change trims the cost for some buyers.
Under the IRS rules for the new car loan interest deduction, owners can deduct up to $10,000 a year in interest for tax years 2025 through 2028, whether or not they itemize. The conditions are narrow.
- The vehicle must be new, with final assembly in the United States.
- The loan must have started after December 31, 2024, and be secured by the vehicle.
- The vehicle must be for personal use.
- The deduction phases out above $100,000 of modified adjusted gross income for single filers and $200,000 for joint filers.
For my hypothetical couple, the first year of a 72-month loan at the average rate carries about $2,930 in interest. In the 12% bracket, the deduction saves roughly $350, or about $29 a month.
How to Check the Share Your Own Payment Takes
Before signing anything at a dealership, run a short calculation with a recent pay stub in hand.
- Add up one month of take-home pay for everyone whose income will cover the car.
- Divide the proposed payment by that total.
- Add insurance quotes, fuel for your actual mileage, and a monthly amount for maintenance, then divide again.
- Compare the loan length with how long you plan to keep the car.
- Ask the dealer for total interest over the loan, not only the payment.
Car Payment Affordability Calculator
See how much of your take-home income goes toward your car, including expenses beyond the loan payment.
YOUR MONTHLY CAR BUDGET
Please enter nonnegative amounts. Income must be greater than zero to calculate a percentage.
This is a budgeting estimate, not a lending decision. It excludes registration, parking, taxes, depreciation and some other expenses. The 10% benchmark uses gross income; it is a general guideline, not a guarantee of affordability. Loan term alone does not determine the remaining loan balance.
By Jalopnik estimates of what the rule requires, financing an average new car that way would take an income near $178,000. For the median household, 10% of gross income is $729 a month, less than the average payment alone.
What the $787 Payment Means for Your Own Budget
For the median household, the record $787 payment takes about one dollar of every nine earned before taxes, and closer to one of every eight after federal taxes. Those shares come from averages.
A used car, a bigger down payment, or a second income can push your share far lower, and a single paycheck can push it far higher. Before the next purchase, run the division on your own take-home pay and on the full cost of driving, not only the loan.
If the salesperson keeps steering back to the monthly payment, ask for the total interest in writing and compare it with the table above.